Fintech leadership in 2026 is increasingly about building the infrastructure behind financial services—not simply launching better banking apps. Payments are becoming more programmable, digital-first banks are operating at enormous scale, artificial intelligence is moving deeper into underwriting and financial operations, and stablecoins are being developed as new settlement rails.
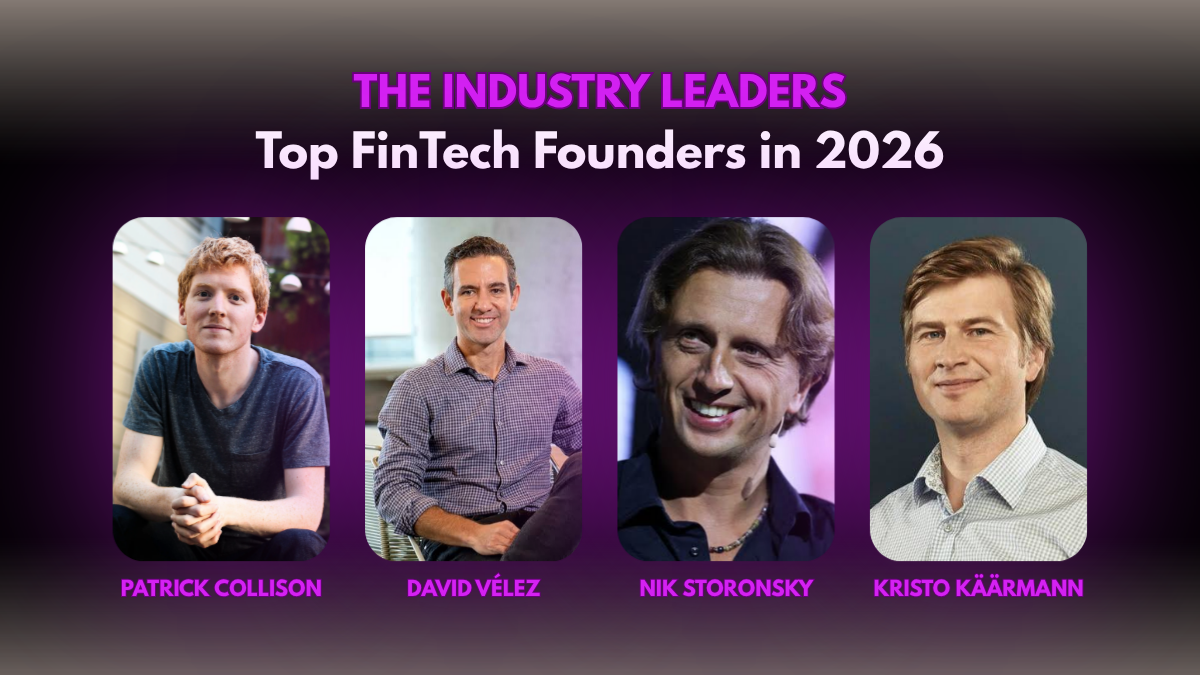
Among the executives shaping these shifts are Patrick Collison of Stripe, David Vélez of Nubank, Nik Storonsky of Revolut, Kristo Käärmann of Wise and Zach Perret of Plaid, alongside leaders working across consumer finance, B2B fintech, digital assets, investing and African payments.
This editorially researched list focuses on ten leaders whose current roles, measurable scale, innovation and activity in 2025–2026 help explain where fintech is heading. The numbering is for readability rather than a score-based ranking.
Leading fintech figures shaping the industry in 2026 include Patrick Collison, David Vélez, Nik Storonsky, Kristo Käärmann, Zach Perret, Sebastian Siemiatkowski, Jeremy Allaire, Eric Glyman, Lalit Keshre and Olugbenga Agboola. Their work spans payments, digital banking, AI, open finance, stablecoins, B2B finance and investing.
Research and company data reviewed through September 17, 2026.
The Top 10 Fintech Leaders of 2026 at a Glance
| Leader | Company | Fintech Focus | What They Are Reshaping | Current Evidence |
|---|---|---|---|---|
| Patrick Collison | Stripe | Payments & financial infrastructure | Programmable commerce and AI-era economic infrastructure | Businesses on Stripe generated $1.9 trillion in 2025 volume |
| David Vélez | Nubank | Digital banking | Mobile-first and increasingly AI-driven banking | 139 million customers in Q2 2026 |
| Nik Storonsky | Revolut | Digital banking | Global multi-product digital banking | 80 million customers by September 2026 |
| Kristo Käärmann | Wise | Cross-border finance | Faster, more transparent international money movement | $243.5 billion in FY2026 cross-border volume |
| Zach Perret | Plaid | Open finance | Financial connectivity evolving into financial intelligence | 500+ million connected accounts and new financial AI models |
| Sebastian Siemiatkowski | Klarna | Payments & consumer finance | Flexible payments expanding into everyday finance | 120 million active consumers in Q2 2026 |
| Jeremy Allaire | Circle | Stablecoins | Programmable digital money and settlement infrastructure | Arc mainnet launched September 16, 2026 |
| Eric Glyman | Ramp | B2B fintech | AI-powered corporate financial operations | $44 billion valuation announced in June 2026 |
| Lalit Keshre | Groww | WealthTech | Mass-market digital investing in India | 23.2 million transacting users as of September 17, 2026 |
| Olugbenga “GB” Agboola | Flutterwave | Payments infrastructure | African and cross-border payment connectivity | More than one billion transactions processed |
How We Selected These Fintech Leaders
There is no single objective measure of who qualifies as a “top” fintech leader, so this list uses a transparent editorial methodology rather than treating company size, valuation or public visibility as sufficient evidence.
We considered each leader’s role in changing how a financial service operates; the measurable scale of the company or infrastructure they lead; meaningful product, technology or business-model innovation; relevance to major fintech developments in 2026; and the broader effect of their work on financial access, cost, speed, competition or infrastructure.
Historical prominence alone was not enough. Each person also needed a credible current-relevance case.
Where possible, quantitative claims are based on regulatory filings, annual reports, investor-relations materials and official company disclosures, supplemented by reputable independent financial reporting when additional context is useful.
1. Patrick Collison — Stripe
Fintech focus: Payments, programmable financial infrastructure and AI commerce
Patrick Collison’s influence on fintech increasingly extends beyond making online payments easier. Stripe, which he co-founded with his brother John, has developed into a broad financial infrastructure platform spanning payments, billing, subscriptions, tax, marketplace payouts, fraud tools and other services businesses use to operate online.
The scale gives that infrastructure significance. Businesses running on Stripe generated $1.9 trillion in total volume in 2025, up 34% from the previous year. Stripe also says its programmable financial services power more than five million businesses, either directly or through platforms.
What makes Collison especially relevant in 2026 is Stripe’s expansion into the economics surrounding artificial intelligence. At its 2026 Sessions event, Stripe announced 288 products and features while continuing to develop infrastructure around agentic commerce and AI-native businesses.
In August, Stripe agreed to acquire OpenRouter, a platform that routes AI requests across more than 400 models from over 80 providers. Stripe framed the move as part of a broader effort to help AI companies manage not only revenue but also model and token costs. The deal had been announced, rather than completed, as of this article’s review date.
The broader fintech significance is the evolution from processing transactions toward supplying programmable infrastructure on which digital businesses increasingly depend.
2026 impact: Collison is helping push payments from a checkout function toward a wider economic layer for internet businesses and AI-enabled commerce.
2. David Vélez — Nubank
Fintech focus: Digital banking, financial access and AI
David Vélez built Nubank around a challenge to traditional Latin American banking: financial services could be delivered through technology with fewer branches, less friction and simpler customer experiences.
That approach has reached substantial scale. Nubank reported 139 million customers globally in Q2 2026, including almost 118 million in Brazil and 16 million in Mexico. The company also surpassed $1 billion in quarterly net income for the first time.
But customer growth is only part of the 2026 story.
Nubank has moved further toward becoming a full banking institution. It launched its bank in Mexico in 2026 and has been expanding its banking structure in Brazil. At the same time, Vélez has made artificial intelligence a central element of the company’s next phase.
Nubank says NuFormer, its foundation-model system for financial behavior, now supports underwriting, customer service and growth decisions. Earlier in 2026, Vélez described the company’s strategy not as adding AI features to traditional banking, but as rebuilding parts of banking around AI.
That creates an important industry case study. Nubank is no longer demonstrating merely that a digital bank can attract customers; it is testing whether a technology-first financial institution can combine enormous scale, profitability, credit and increasingly AI-enabled decision-making.
2026 impact: Vélez illustrates how a neobank can evolve into a major financial institution while retaining a digital-first operating model.
3. Nik Storonsky — Revolut
Fintech focus: Global digital banking and multi-product finance
Revolut began with a relatively narrow proposition around foreign exchange and international spending. Under co-founder and CEO Nik Storonsky, it has expanded into accounts, payments, cards, savings, investing, business services and other financial products.
By September 2026, Revolut was serving 80 million customers globally, according to Reuters. The company generated approximately $6 billion in revenue and $2.3 billion in pretax profit in 2025.
Its ambitions increasingly resemble those of a global bank rather than a standalone fintech app. Revolut received conditional approval for a U.S. national banking charter in September 2026 and has continued pursuing banking licenses and expansion in other markets.
That scale, however, also changes the standard by which the company must be judged.
In September 2026, Revolut confirmed a breach involving sensitive customer information after fraudulent requests impersonating a government source. The incident is relevant not because it changes the company’s growth story, but because it highlights the security and trust obligations that come with becoming a large regulated financial institution.
Storonsky’s larger experiment is therefore about more than product breadth. Revolut is testing whether a digitally native financial platform can operate across countries, products and regulatory regimes while maintaining the trust expected of a bank.
2026 impact: Storonsky is pushing the financial-super-app model toward something closer to a genuinely international banking institution.
4. Kristo Käärmann — Wise
Fintech focus: Cross-border payments and international financial infrastructure
International money transfers have historically involved hidden exchange-rate markups, intermediary fees and payment chains that can make moving money across borders slow and expensive.
Kristo Käärmann co-founded Wise to address that problem through more transparent pricing and a different approach to international money movement.
Wise served 18.9 million active customers in FY2026 and processed $243.5 billion in cross-border volume, up 31% year over year. It also reported that 75% of its Q4 payments globally were completed in under 20 seconds.
The more important semantic shift is what Wise is becoming.
The business now connects directly to domestic payment systems in a growing number of markets and provides its infrastructure to banks and other institutions through Wise Platform. During FY2026, it added direct payment-system connections in Brazil and Japan, secured additional regulatory approvals and added new institutional partners.
That means Wise increasingly operates at two layers. Consumers and businesses can use Wise directly, while other financial institutions can embed its cross-border infrastructure into their own products.
This movement from standalone international-transfer service toward an underlying network is what makes Käärmann particularly relevant to the modern fintech story.
2026 impact: Käärmann is helping turn cross-border payments from a separate financial product into infrastructure that can be embedded inside other financial services.
5. Zach Perret — Plaid
Fintech focus: Open finance, financial data and AI
Much of modern fintech depends on infrastructure that customers rarely see: the technology connecting financial accounts, applications and data.
Plaid, co-founded and led by Zach Perret, has become a major part of that connectivity layer. The company says its network spans more than 12,000 financial institutions, covers more than 500 million connected accounts, and has been used by one in two U.S. adults with a bank account.
Historically, Plaid’s central role was helping financial applications connect securely to bank accounts.
In 2026, Perret is pushing the company toward what Plaid calls a financial intelligence layer.
At Plaid Effects in May, the company announced foundation models trained specifically on large-scale financial data for uses spanning fraud, credit, payments and financial management. Plaid reported improvements in areas such as transaction categorization and income classification from the models it has begun deploying.
The distinction is significant.
Connectivity tells an application what transactions and balances exist. Financial intelligence attempts to interpret those activities and identify patterns that may be useful for underwriting, fraud prevention or personalized financial products.
That makes Plaid an example of AI moving below the visible consumer interface and into the data infrastructure on which financial applications rely.
2026 impact: Perret is attempting to evolve open-finance connectivity into an intelligence layer for financial products.
6. Sebastian Siemiatkowski — Klarna
Fintech focus: Flexible payments, consumer finance and everyday banking
Sebastian Siemiatkowski remains closely associated with buy now, pay later, but Klarna’s current strategy extends well beyond installment checkout.
The company increasingly describes itself as an everyday finance network linking consumers and merchants.
Klarna reported 120 million active consumers, more than 1.2 million merchants, $36.6 billion in quarterly GMV and $1.042 billion in Q2 2026 revenue. It also reported positive net income for the quarter.
Its product mix is broadening as well. Klarna Card had reached 6.5 million active users across 16 countries, while memberships and longer-term financing were contributing to deeper customer engagement. The company has also applied for a U.S. banking charter, saying broader banking capabilities could help it serve customers across spending, saving and payments.
This changes how Siemiatkowski’s impact should be understood.
Klarna originally met customers at checkout. Its current ambition is to convert that momentary transaction relationship into a broader financial relationship that may extend across cards, credit, payments and banking-like services.
Whether that transformation succeeds will depend on more than customer acquisition. Credit performance, funding costs, regulation and responsible lending remain fundamental to any business expanding deeper into consumer finance.
2026 impact: Siemiatkowski is testing whether a flexible-payments network can grow into a broader everyday-finance platform.
7. Jeremy Allaire — Circle
Fintech focus: Stablecoins, programmable money and digital settlement
Stablecoins increasingly sit at the intersection of blockchain technology and conventional financial infrastructure. Jeremy Allaire, Circle’s co-founder, CEO and chairman, has spent years positioning USDC around that intersection.
Circle reported $73.3 billion of USDC in circulation at the end of Q2 2026 and $14.8 trillion in on-chain USDC transaction volume during the quarter.
That second number needs context.
On-chain stablecoin transaction totals are not equivalent to consumer and merchant payments. Trading, arbitrage, internal transfers and other crypto-native activity account for a large share of blockchain volume. McKinsey and Artemis Analytics estimated actual stablecoin payments across the broader market at approximately $390 billion in 2025, only a small fraction of headline stablecoin transaction volumes.
Circle’s most important 2026 development may therefore be infrastructure rather than raw volume.
On September 16, 2026, Circle launched the public mainnet of Arc, a Layer-1 blockchain designed around financial markets, real-time money movement and agentic economic activity. Circle said more than 100 institutional and ecosystem builders were involved at launch, with participants spanning banks, asset managers, payment companies and technology platforms.
That brings Circle’s strategy beyond simply issuing a stablecoin. The company is attempting to build a wider ecosystem for settlement, tokenized financial activity and programmable money.
2026 impact: Allaire is pushing stablecoins toward a role as regulated, programmable financial infrastructure rather than treating them primarily as crypto-market instruments.
8. Eric Glyman — Ramp
Fintech focus: B2B fintech, corporate finance and AI automation
Some of fintech’s most consequential changes are occurring away from consumer banking screens and inside corporate finance departments.
Eric Glyman co-founded Ramp around corporate cards and expense management, but the company’s product footprint has expanded into accounts payable, procurement, travel, treasury and other financial operations.
Ramp said in March 2026 that its platform was serving more than 50,000 customers, while its enterprise customer base had grown 133% during 2025.
In June, Ramp announced new funding at a $44 billion valuation while describing AI-related spending as an emerging third category of corporate expenditure alongside people and traditional vendors.
The leadership structure changed later that month when Glyman and co-founder Karim Atiyeh formally became co-CEOs.
Ramp’s larger relevance is not simply that it makes expense management easier.
The company represents a shift from software that records and reconciles company spending toward systems intended to control, automate and increasingly interpret financial operations as they happen. AI raises the possibility of automating more of that work, while also creating new categories of spend that finance teams need to govern.
2026 impact: Glyman is helping move B2B fintech from digitizing financial administration toward automating parts of corporate finance itself.
9. Lalit Keshre — Groww
Fintech focus: WealthTech and mass-market investing in India
India’s fintech transformation is not limited to payments and digital banking. Retail investing and digital wealth platforms are also bringing financial products to a much larger population.
Lalit Keshre, Groww’s co-founder and CEO, helped build the company around making investment products simpler to access through a digital-first interface. His current role is listed as whole-time director and CEO.
Groww began with mutual funds and has expanded across stocks, ETFs, IPOs, derivatives, commodities and credit products.
As of September 17, 2026, its investor-relations site reported 23.2 million transacting users and approximately ₹3.71 trillion in customer assets.
Those figures matter because India presents a very large opportunity for digitizing saving and investing.
Groww’s role is less about inventing a new financial asset than changing distribution: products that historically required greater financial familiarity or more fragmented access can increasingly be reached through a single mobile platform.
The same growth creates responsibility. Broader access to sophisticated products such as derivatives also increases the importance of investor education, risk disclosures and suitable product design.
2026 impact: Keshre represents fintech’s role in expanding digital participation in investing and wealth products across India.
10. Olugbenga “GB” Agboola — Flutterwave
Fintech focus: African payments, cross-border commerce and financial infrastructure
African businesses often operate across markets with different currencies, payment systems, mobile-money networks, banks and regulatory structures. Connecting those systems is a financial-infrastructure problem.
Olugbenga “GB” Agboola, founder and CEO of Flutterwave, has spent much of the past decade building around that fragmentation.
By July 2026, Flutterwave said its infrastructure had processed more than one billion transactions worth over $50 billion. Its platform connects banks, cards, mobile money and local payment systems so businesses can operate across multiple markets without building every integration independently.
The company is also expanding the kinds of rails running through that infrastructure.
Flutterwave brought open-banking company Mono into its ecosystem in 2026, while partnerships and investments involving Circle and Ripple have expanded its use of stablecoin-based settlement alongside conventional payment methods.
This “multi-rail” approach is important because African fintech does not operate on one universal payment system. Cards, bank transfers, mobile money and newer digital settlement technologies may all be relevant depending on the market and transaction.
Flutterwave’s role is therefore less about promoting one payment technology than creating an interoperability layer between fragmented systems.
2026 impact: Agboola is helping build financial infrastructure that connects African businesses and payment systems with regional and global commerce.
What These Fintech Leaders Reveal About the Industry in 2026
Looking across these ten leaders is more useful than treating them as ten unrelated founder stories. Their companies reveal several broader changes in financial technology.
AI Is Moving From Features Into Financial Infrastructure
The first phase of AI adoption in financial services often focused on customer-service assistants and employee productivity tools.
Some 2026 fintech strategies go considerably deeper.
Nubank’s NuFormer is being used in underwriting and financial-behavior analysis. Plaid has developed financial-data foundation models for fraud, credit, payments and money management. Ramp is building controls around AI-generated corporate spending, while Stripe is expanding the economic infrastructure surrounding AI businesses and agentic commerce.
That creates both opportunity and risk.
AI systems involved in lending, fraud detection, transactions or autonomous financial activity operate much closer to consequential financial decisions than a basic chatbot. The World Economic Forum’s 2026 work on AI in financial services consequently emphasizes data quality, accountability, governance, security and human oversight alongside technological adoption.
Fintechs Are Moving Deeper Into Banking
The earlier fintech model often involved building better interfaces or specialized products on top of existing banking infrastructure.
That separation is weakening.
Nubank already operates at major financial-institution scale. Revolut continues pursuing banking licenses across markets. Klarna is attempting to broaden a checkout relationship into spending, saving and other everyday financial services.
McKinsey notes that fintech companies increasingly view banking licenses not simply as regulatory burdens but as strategic assets that can provide cheaper funding, wider product capabilities and stronger customer trust.
The consequence is a trade-off.
As fintech companies become more bank-like, they also inherit more bank-like responsibilities: regulation, capital management, lending risk, compliance, cybersecurity and operational resilience.
Payments Are Becoming Infrastructure
Stripe, Wise and Flutterwave began with different customer problems, but their evolution shows a similar pattern.
The visible payment experience is only one layer of the business.
Stripe provides APIs and financial services that other businesses build into products. Wise increasingly supplies cross-border infrastructure to banks and enterprises. Flutterwave connects multiple payment methods and local systems across fragmented markets.
This moves fintech from selling a payment product toward providing financial rails that other companies depend on.
The distinction matters because infrastructure can create deeper relationships than standalone consumer applications. Once other companies build financial products around those systems, the fintech provider becomes part of the underlying architecture rather than simply another app competing for attention.
Stablecoins Are Moving Toward Payment and Settlement Rails
Stablecoin headlines often focus on enormous blockchain transaction numbers, but those figures can exaggerate their use in normal commercial payments.
McKinsey estimates that actual end-user stablecoin payments accounted for approximately $390 billion in 2025, compared with roughly $35 trillion in reported annual blockchain transaction activity. Most volume still comes from trading, arbitrage and other crypto-native activity.
The smaller payment figure does not make the category irrelevant. It clarifies what stage the technology is actually in.
Circle is building Arc and its payment infrastructure around settlement and programmable finance. Flutterwave is incorporating stablecoin settlement into African cross-border payments. Stripe is also integrating stablecoins into broader commercial financial infrastructure.
The important fintech question is therefore not whether stablecoins generate large blockchain volumes. It is whether they can reduce friction in specific financial use cases while meeting the compliance, liquidity, reliability and trust requirements businesses expect.
B2B Fintech Is Becoming a Major Frontier
Fintech’s early consumer appeal came largely from replacing frustrating financial experiences with easier digital products.
Enterprise finance represents a different opportunity.
Companies still manage cards, procurement, expenses, invoices, accounting and treasury through complicated combinations of software and manual processes.
Ramp represents the attempt to unify and automate more of those workflows. Stripe provides underlying commercial infrastructure, while Plaid supplies data and connectivity capabilities that businesses and financial institutions can use.
McKinsey’s 2026 fintech analysis similarly identifies a growing class of “horizontal” fintechs that enable or modernize existing financial companies rather than directly competing with them for consumers.
This means the next major fintech product may be something consumers never directly see.
Emerging Markets Are Producing Distinct Fintech Models at Massive Scale
David Vélez, Lalit Keshre and GB Agboola illustrate another major shift.
Important fintech models increasingly originate from financial problems that look different from those in the United States or Western Europe.
Nubank emerged from the structure and costs of Latin American banking. Groww is helping expand digital participation in India’s investing market. Flutterwave is tackling payment fragmentation and cross-border connectivity across African economies.
These companies are not merely exporting a Silicon Valley financial product to new geographies.
Different banking structures, payment rails, regulations, customer behaviors and access challenges create different problems—and therefore different forms of fintech innovation.
Scale Is Making Trust, Regulation and Profitability Part of the Fintech Moat
Fintech disruption was once strongly associated with speed: move faster than banks, build better software and remove friction.
At larger scale, that is no longer enough.
McKinsey estimates that the global fintech industry generated approximately $650 billion in revenue in 2025, with the industry’s more mature companies increasingly balancing growth with profitability, operational discipline and regulatory capability.
That shift is visible across this list.
Nubank, Revolut and Klarna are moving deeper into regulated banking. Circle is linking digital assets to more institutional financial infrastructure. Plaid, Ramp and Nubank are applying AI closer to important financial decisions.
As these systems become more consequential, competitive advantage increasingly includes cybersecurity, governance, regulatory permissions, reliable infrastructure and customer trust.
The next stage of fintech competition may therefore be defined not simply by which company ships features fastest, but by which companies can combine technological speed with the reliability expected from financial institutions.
The Bigger Picture: Where Fintech Leadership Is Heading
The leaders on this list point to a fintech industry that looks increasingly different from the app-led disruption narrative of the previous decade.
Financial technology is moving from apps toward infrastructure, as companies such as Stripe, Wise, Plaid and Flutterwave become underlying layers other businesses depend on.
It is moving from digitization toward intelligence, as Nubank, Plaid and Ramp put AI deeper into financial decisions and operations.
It is moving from narrow products toward broader financial ecosystems, as Nubank, Revolut and Klarna compete for larger shares of their customers’ financial lives.
And it is expanding the definition of financial rails themselves. Circle’s launch of Arc reflects efforts to bring programmable digital money into mainstream financial infrastructure, while Groww and Flutterwave show how major fintech models are being shaped by markets outside traditional Western technology centers.
The most influential fintech leaders of the next phase may therefore be those who do more than launch another financial product. Their larger challenge will be building the infrastructure, intelligence, access and trust systems through which money moves.
